Planned business line · Regulated services through licensed partners
Fintech.
Turning records into credit.
Illustration. A proposed model, not an AVERON facility or completed project.
The opportunity
A farmer who delivers and repays leaves a useful record. We plan to connect that record to payments, credit and equipment finance through licensed providers, starting with the agricultural delivery cycle.
Global estimate in the 2019 report; not a Uganda market-size claim
PlannedAVERON is not a licensed bank, lender or payment provider. Regulated services would be delivered through appropriately licensed partners or follow the required licensing process. Product terms and providers are not yet confirmed.
East Africa now
Payment rails have scale
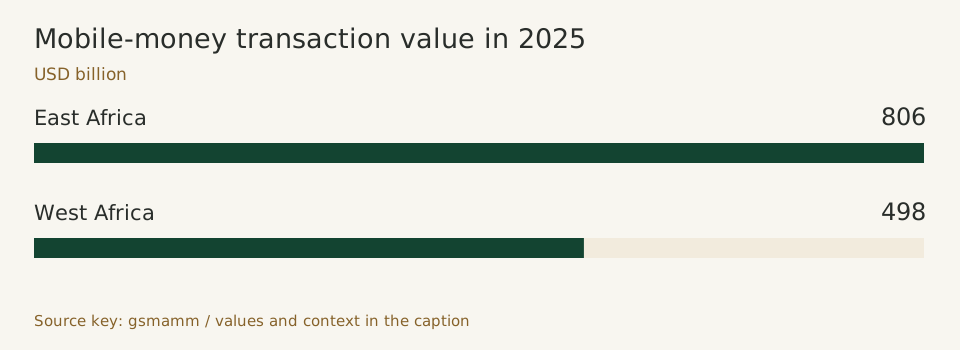
GSMA reports USD 806bn in East African mobile-money transactions in 2025. Transaction volume demonstrates use of the payment channel; it does not tell us whether a borrower can afford a loan. Credit assessment still needs income, costs and repayment evidence.92
A delivery record can improve an application
The cited Agricultural Credit Facility report put approvals at 57% of 7,726 applications. AVERON’s proposed contribution is a clearer crop-delivery and repayment record, with a lender retaining responsibility for its credit decision and the customer’s terms.70,76
Remittances and agricultural cash flow differ
Remittance reporting describes Shs 9.6trn in annual inflows, with 61% arriving through mobile money. Farm income is seasonal. A finance product for seed or a pump would need a repayment schedule matched to the customer’s actual income.86
Licensing determines the route
Payment services, lending and other regulated products have distinct rules. We plan to identify the appropriate licensed provider for each service, agree responsibilities for customer checks and complaints, and confirm permissions before offering it.84,85
GSMA regional transaction flows. These are payment values, not financial-sector earnings or available credit.92A farmer takes a call in her field in Kenya. Illustrative photo. Photo: Neil Palmer, CIAT, CC BY-SA 2.0, via Wikimedia Commons. Resized for the web.
What AVERON will do
Stages describe the proposed sequence. Progress depends on the decision gate for each stage; no commissioning date is promised.
NowAgricultural model / in development
Record credit and delivery
Develop the input-credit model around cooperative records and recovery at crop delivery; record what was advanced, delivered, deducted and paid.76
Decision gateClear customer terms and a reconciled delivery and deduction record.
NextPlanned / partner dependent
Connect payments and histories
Arrange digital payments through licensed providers and consent-based sharing of suitable repayment records.
Decision gateA confirmed provider, lawful sharing and a customer complaints process.
LaterPlanned / regulated
Finance productive assets
Explore pay-as-you-go and lease-to-own for solar, pumps, tractors and electric motorcycles, plus savings and insurance links with licensed providers.
Decision gateAffordability assessment, product approval and verified servicing capacity.
What the capability includes
Payment reconciliation
Connect a delivery, its deductions and a payment confirmation so disputes can be resolved.
Credit histories
Share an accurate, correctable record with permission; the lender decides what credit to offer.
Equipment-finance links
Proposed partner products that consider asset maintenance as well as repayment.
Inputs / productive asset
Farm + earn
Deliver / reconcile
Repay + build history
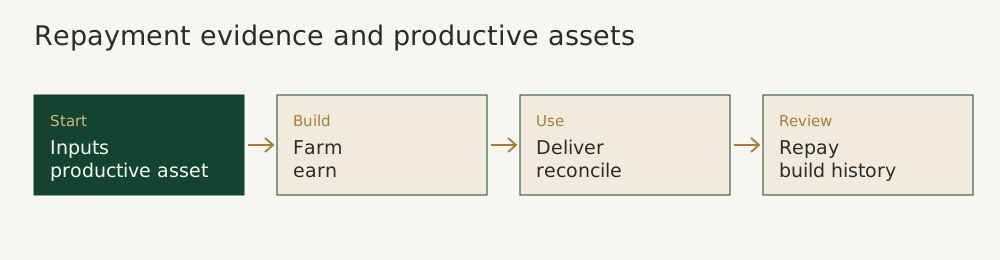
Repayment evidence and productive assets. Proposed sequence; each stage requires its own checks.76A farmer harvests maize in Central Region, Uganda. Illustrative photo. Photo: Mwesigwa Joel, Pexels licence, via Pexels. Resized for the web.
How it earns
These are proposed arrangements. Contracts, pricing, operating costs and any regulatory permissions would be confirmed for each activity.
Services and commissions
Agreed service fees and licensed-partner commissions, disclosed under applicable product rules.
Agricultural input credit
A margin on the input-credit model, subject to confirmed legal structure and customer terms.
Partner asset finance
A proposed share of service or finance income through appropriately licensed partners, with responsibilities specified.
No credit product, rate, return or approval is promised. A payment history is evidence for assessment, not a guarantee that a loan will be made.76
How it connects
Agriculture would provide delivery and repayment records. Data would help validate them; IT would secure the systems. Licensed finance partners could support assets used in Energy and mobility and Agriculture, with asset ownership and servicing obligations made explicit.
We welcome discussions around a defined project, capability or delivery need. The structures below are starting points for discussion, not an offer of securities or a promise of returns.
Technology partnership
You bringEquipment, software or specialist operating experience.
AVERON bringsA local use case and a staged route to testing it.